
CRA Audit Help for Canadian Businesses
If you have received a CRA audit letter, you generally have 30 days to respond. Elliott & Lee Business Management LTD represents Canadian businesses through CRA audits, reviews, reassessments and objections — we take over correspondence with the Canada Revenue Agency, assemble and defend your documentation, and negotiate the outcome. Our tax controversy practice is led by Abdul Hameed Khan, who holds a Master of Laws (LLM) in Taxation and a CPA designation. Our team has handled more than 100 CRA audits. We work from offices in Penticton and Vancouver, British Columbia, and act for clients across Canada.
Free 30-minute CRA Audit Assessment — bring the letter, leave with a plan.
Request your free 30-minute assessment
Key facts about CRA audits
Most CRA review or audit letters require a response within 30 days. Extensions can often be arranged — but only if you ask before the deadline.
Most audits run 3 to 12 months, depending on complexity and how quickly information is provided.
Generally 3 years from your original notice of assessment. Where the CRA alleges misrepresentation, neglect, carelessness or fraud, there is no time limit.
You can file a Notice of Objection within 90 days of the assessment, under s.165(1) of the Income Tax Act.
A gross negligence penalty of 50% of the understated tax where the CRA finds a knowingly false statement.
Receipts, proof of income, invoices, bank statements, and clarification of specific claims. Incomplete answers escalate the review.
Sources: Canada Revenue Agency (canada.ca) on reviews, audits and penalties; Income Tax Act, s.165(1).
The CRA sends an auditor. You get a specialist trained in tax law, accounting and audit — in one person.
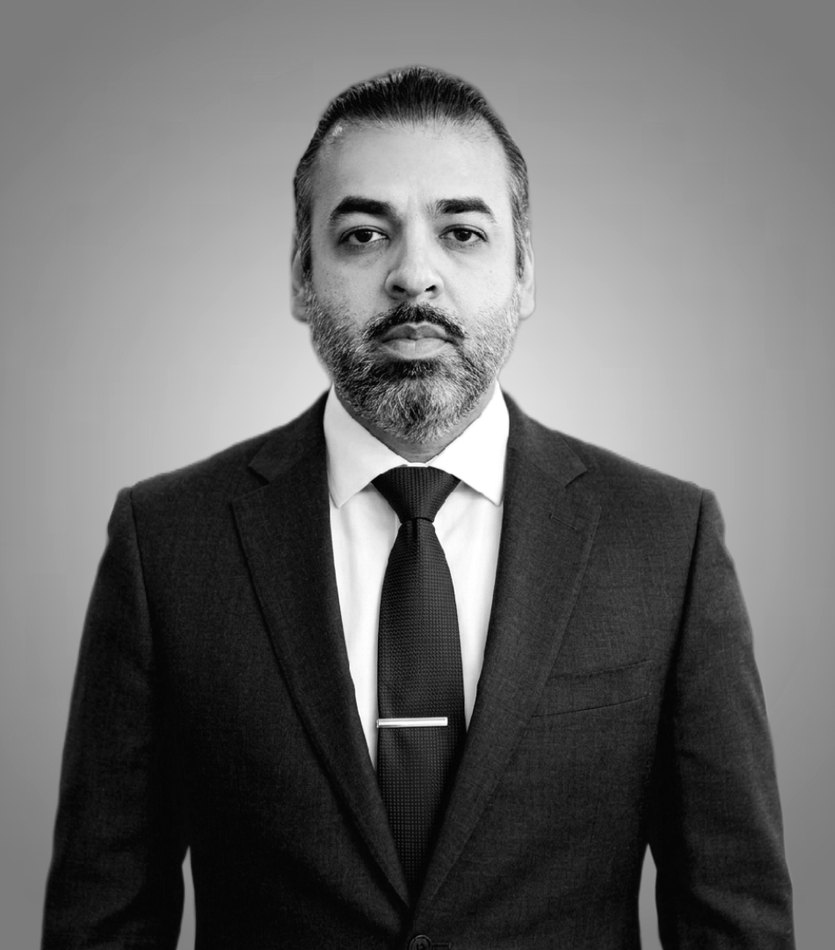
Abdul Hameed Khan leads tax controversy at Elliott & Lee.
Read Hameed's full profileThe tax-law grounding for objections, appeals and technical positions, not just filing
Chartered Professional Accountant (CPA British Columbia)
Institute of Internal Auditors, United States
Certification in Risk Management Assurance (IIA, United States)
Association of Chartered Certified Accountants
In tax, audit and risk
Backed by Elliott & Lee's 20+ years of combined experience, qualified staff, and more than 100 CRA audits handled by our team.
And we audit for a living. As a Certified Internal Auditor, Hameed has spent his career building and testing the exact controls the CRA comes looking for. An audit stops being a mystery when you have run hundreds of them from the other side of the table.
What to do in the first 30 days
- Don't ignore it, and don't improvise. The 30-day clock is real, and a missed deadline turns a review into a proposal letter and then a formal reassessment.
- Don't call the CRA to explain. Unscripted explanations become part of the file. Anything you say can widen the scope of the audit.
- Read what is actually being asked. A document request on one expense category is a very different problem from a full field audit. They are routinely confused.
- Don't send everything you have. Over-disclosure invites new questions. Send what was requested, complete and organised.
- Get a specialist in front of the auditor. You can appoint a representative to handle all CRA contact on your behalf.
That last step is what we do. From the day you appoint us, the CRA deals with Elliott & Lee — not with you at 11pm with a box of receipts.
Request your free 30-minute assessmentWhat that actually means
You don't face the CRA alone — we take it off your desk
From the day you appoint us, the Canada Revenue Agency deals with Elliott & Lee, not with you. Every letter, every phone call, every document request comes to us. You stop being the one at 11pm with a box of receipts trying to work out what they're actually asking.
Whatever they've sent you, we've answered it before
Corporate tax (T2) audits, GST/HST and PST reviews, payroll and source-deduction audits, shareholder loan and benefit reviews, unreported income, net worth assessments, denied expenses. Our team has handled more than 100 CRA audits. There is very little the CRA can open that we haven't seen before.
We don't stop when the assessment arrives
If the CRA gets it wrong, that's not the end of it. We file the Notice of Objection inside the 90-day window, argue the technical position, and pursue penalty and interest relief where the facts support it.
Recent CRA audit, review and dispute matters
We represent businesses and individuals facing CRA audits, reviews, expense challenges, reassessments, information requests and other Canadian tax disputes. These are examples of matters where we helped clients substantiate their tax position and get through CRA scrutiny. Details are anonymised to protect client confidentiality.
CRA audit of intercompany management fees
What the CRA questioned: whether the intercompany management fees were deductible. That turned on whether the underlying services were genuine and the charges adequately supported.
What we did: reviewed the underlying arrangements and supporting records, and established the commercial substance of the management services. Organised the documentation around each of the CRA's specific concerns, then engaged directly with the CRA through a detailed written response.
Outcome: resolved on terms agreed between the client and the CRA.
CRA challenge of advertising and marketing expenses
What the CRA questioned: whether the advertising and marketing expenses were legitimate business expenses, with enough support for the tax treatment claimed.
What we did: analysed the expenses and supporting records, identified the business purpose behind each one, and answered the CRA's questions. Filed a final submission connecting every document to the commercial rationale for the marketing activity.
Outcome: the CRA's concerns were addressed and the matter was resolved.
CRA disallowance of business expenses
What the CRA did: during a tax review, disallowed expenses that the client maintained were legitimate costs incurred in the ordinary course of business.
What we did: challenged the CRA's proposed treatment. Reviewed each disallowed expense in detail, assembled the relevant records, and prepared a response showing how each expense connected to the client's business activities.
Outcome: the CRA accepted our position in full.
CRA review of donation claims
What the CRA questioned: the donation amounts claimed, with a request for further support.
What we did: reviewed the records and assessed each of the CRA's questions. Organised the supporting evidence and prepared a focused response to each issue the review raised.
Outcome: resolved successfully on the clients' behalf, supported by documentation and explanations.
Dividend tax credit reporting between spouses
What the CRA questioned: how dividend income and the related dividend tax credit had been reported between the spouses in a prior-year return.
What we did: reviewed the prior-year filings, identified the issue behind the CRA's inquiry, reconstructed the filing position, and set out the legal basis for the dividend tax credit treatment in direct correspondence with the CRA.
Outcome: resolved successfully through CRA correspondence and clarification of the filing position.
Employment expenses (Form T2200)
What the CRA questioned: employment expenses claimed in a prior year, relating to the taxpayer's office or conditions of employment, with a request for evidence that they were deductible.
What we did: reviewed each expense and compiled the supporting documents, including the Declaration of Conditions of Employment (Form T2200). Prepared a report with schedules showing the circumstances in which each expense was incurred.
Outcome: the client's position was substantiated and the CRA's concerns were resolved.
A CRA letter is not the final word
A letter from the CRA does not mean the CRA's initial position is the final outcome. CRA audits and tax disputes are often won or lost on the quality of the evidence, the technical position taken, and how clearly that position is communicated to the CRA.
What we handle

Business and corporate audits
- Corporate income tax (T2) audits and reviews
- GST/HST and PST audits, including input tax credit disputes
- Payroll and source-deduction audits
- Shareholder benefit and shareholder loan reviews
- Unreported income and net worth assessments
- Expense and deduction denials
Disputes and resolution
- Notices of Objection, filed within the 90-day window
- Appeals and technical position development
- Penalty and interest relief applications (taxpayer relief)
- Voluntary Disclosure Program (VDP) applications
- Negotiated settlements and payment arrangements
Before an audit happens
- Audit risk reviews and documentation gap analysis
- Compliance framework and internal control design
- Ongoing CRA correspondence handling
- Dividend tax credit and employment expense (T2200) reviews
- CRA information requests
How we work

Understand what the CRA is really questioning

Reconstruct the facts

Build the documentary evidence

Develop the tax position

Engage the CRA with a clear, defensible response
What an engagement looks like
1. Free 30-minute assessment. Tell us what the CRA sent you and the date on the letter. We come back to you promptly to set up the call, and we tell you what is actually being asked, how exposed you are, and what we would do — whether or not you engage us.
2. We take over the correspondence. You appoint Elliott & Lee as your representative. From that point the CRA's questions come to us.
3. We build the file. Documentation assembled, reconciled and presented the way an auditor expects to receive it — which is the difference between a closed audit and an expanded one.
4. We defend the position. Where the CRA proposes an adjustment we challenge it on the technical merits, and where an assessment has already landed we file the objection.
5. You get your week back.
Institutions, charities and public-sector organizations
Elliott & Lee also advises institutions, registered charities and public-sector bodies on CRA matters — where an audit is less often about unreported income and more often about indirect tax exposure, rebate positions and control frameworks.
- GST/HST cyclical reviews and transaction-based indirect tax advisory
- Ongoing CRA dialogue on audits, reviews and filings, acting as external advisor alongside an in-house finance team
- Canadian Charities Returns (T3010) and charity compliance reviews
- Tax control framework reviews and risk assessment
- GST training for finance and administrative personnel
Hameed's Certified Internal Auditor and Risk Management Assurance credentials are directly relevant here: institutional CRA work is control-and-documentation work, assessed the way an internal audit function is assessed.
Discuss your institutional needsMost audits are lost long before the letter arrives
By the time the CRA writes to you, the outcome is largely already sitting in your books — in the gaps, the unexplained deposits, the shareholder draws nobody documented. The cheapest audit defence is the one built before it is needed.
Free 30-minute Audit Risk Review. We look at your file the way an auditor would, and tell you what to fix first.
Request your free risk reviewFrequently asked questions
How long do I have to respond to a CRA audit letter?
Most CRA review and audit letters require a response within 30 days of the date on the letter. Extensions are often available if you request one before the deadline passes. Missing the deadline without contact typically results in a proposal letter followed by a formal reassessment based on the CRA's own assumptions.
Can an accountant represent me during a CRA audit?
Yes. You can authorise a representative to deal with the Canada Revenue Agency on your behalf, and from that point the CRA directs its questions and document requests to them rather than to you. At Elliott & Lee this work is led by Abdul Hameed Khan, who holds both a CPA designation and a Master of Laws (LLM) in Taxation.
Should I just call the CRA and explain?
It is rarely a good idea to give the CRA an unscripted explanation. Anything you say becomes part of the audit file and can widen the scope of the review. Respond in writing, provide exactly what was requested, and have a representative manage the exchange.
How far back can the CRA audit me?
The normal reassessment period is generally three years from the date of your original notice of assessment. Where the CRA alleges misrepresentation attributable to neglect, carelessness, wilful default or fraud, there is no time limit on how far back it can reassess.
How long does a CRA audit take?
Most CRA audits take between three and twelve months. The main variables are the complexity of the issues and how quickly and completely information is provided. Disorganised or partial responses are the most common cause of an audit dragging on.
What happens if I disagree with the audit result?
You can file a Notice of Objection within 90 days of the date of the assessment, under s.165(1) of the Income Tax Act. This moves the file to the CRA's Appeals division for independent review. Missing the 90-day window sharply limits your options, so the deadline matters as much as the argument.
Can CRA penalties be reduced or cancelled?
Sometimes. Gross negligence penalties of 50% of the understated tax can be challenged where the facts do not support a finding that a false statement was made knowingly. Separately, the taxpayer relief provisions allow the CRA to cancel or waive penalties and interest in circumstances such as serious illness, financial hardship or CRA error.
What triggers a CRA audit?
Common triggers include large or unusual changes year over year, expense ratios out of line with industry norms, repeated losses, significant shareholder loans or draws, GST/HST refund claims, cash-intensive operations, and mismatches between reported income and third-party information slips.
What documents will the CRA ask for?
Typically receipts and invoices, bank and credit card statements, general ledger and source records, payroll records, and explanations of specific claims or deposits. Provide what was requested, complete and organised. Sending more than was asked for tends to generate new questions.
Do you only work with businesses in Penticton and Vancouver?
No. Elliott & Lee has offices in Penticton and Vancouver, British Columbia, and represents clients throughout Canada. CRA audits are federal, and audit representation is handled by correspondence, phone and video, so location is not a constraint.
Don't answer the CRA alone. From today, they talk to us.
Every letter, every call, every document request — routed through a tax specialist instead of through you. Free 30-minute assessment, no obligation, and you'll leave it knowing where you stand.
Tell us what the CRA sent you and the date on the letter, and we'll come back to you promptly.
Request your free 30-minute assessmentPenticton: 246 Martin St #105, Penticton BC V2A 5K3 · (778) 476-1547
Vancouver: 938 Howe St, Office 607, Vancouver BC V6Z 1N9 · (778) 476-1547
admin@elliottandlee.com
Contact us today to get a free consultation!
Tell us what the CRA sent you and the date on the letter. We'll get back to you promptly to set up your free 30-minute review.


